Oracle Corporation (NYSE:ORCL) is facing growing scrutiny over the financing of its AI infrastructure after about $18 billion of loans tied to its Project Jupiter data center in New Mexico were quoted at 89 to 91 cents on the dollar, according to the Financial Times, as reported by Reuters.
The project is part of Oracle’s AI infrastructure expansion with OpenAI, but local opposition over water and air-quality concerns and a regulatory setback involving a proposed natural-gas pipeline have raised questions about its development. Banks have also struggled to distribute the debt to other investors as concerns about Oracle’s leverage have increased. Reuters noted that S&P downgraded Oracle in July to one notch above junk.
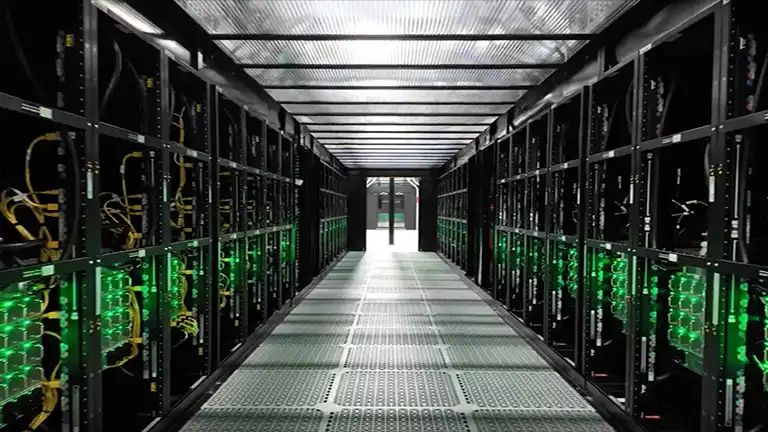
Photo from Oracle website
Oracle’s AI Backlog Could Provide a Cushion for Rising Financing Needs
The debt pressure is occurring alongside exceptionally strong demand for Oracle Corporation’s cloud infrastructure. In the first quarter of fiscal 2027, cloud revenue rose 62% to $11.6 billion, while cloud infrastructure revenue increased 121% to $7.4 billion. Oracle’s remaining performance obligations also reached $664 billion, up $209 billion year over year, providing substantial contracted demand to support continued infrastructure investment.
The financing model is also becoming less dependent on Oracle funding every dollar itself. Oracle said $75 billion of its large AI contracts involved customers prepaying for GPUs or supplying the GPUs themselves, substantially reducing the capital it needs to raise for AI data centers. Oracle raised $43 billion of debt and $5 billion of equity in fiscal 2026, while expecting about $40 billion of additional debt and equity financing in fiscal 2027. If customer-backed contracts continue expanding, the revenue generated from infrastructure could increasingly offset the financing burden.
Rising Infrastructure Costs Could Test Oracle’s AI Investment Strategy
The immediate concern is that Oracle Corporation is committing capital faster than its infrastructure generates cash. Capital expenditures jumped to $55.7 billion in fiscal 2026 from $21.2 billion a year earlier, producing negative free cash flow of $23.7 billion. In the first quarter of fiscal 2027 alone, capital expenditures reached $28.5 billion, and Oracle expects fiscal 2027 spending to exceed the prior year.
The balance sheet leaves less room for execution problems. As of August 31, Oracle had $125.3 billion of notes payable and other borrowings, compared with $37.1 billion of cash and marketable securities. It also had $34.6 billion of recognized operating lease liabilities and another $288 billion of additional data-center lease commitments expected to begin between fiscal 2027 and fiscal 2029.
Project Jupiter therefore matters beyond the $18 billion financing itself. If permitting, power availability, or local opposition delays the facility, Oracle could face infrastructure costs before the associated capacity becomes productive. That risk is particularly relevant because the company’s cloud and software margin percentage already declined in the latest quarter as higher infrastructure expenses supported cloud growth.
Conclusion
Oracle Corporation’s AI opportunity remains supported by rapidly growing cloud infrastructure revenue and $664 billion of remaining performance obligations. But the Project Jupiter debt issue highlights the financial risk of pursuing that opportunity through aggressive infrastructure spending and leverage.
With more than $125 billion of borrowings, negative free cash flow, and another year of rising capital expenditures, delays or weaker-than-expected utilization of new data centers could put greater pressure on cash flow, financing costs, and valuation. The key issue is whether Oracle can convert its unusually large AI backlog into cash generation quickly enough to justify the debt and infrastructure commitments.
READ NEXT: This Underrated Bank Stock Just Raised its Dividend for the 11th Straight Year and Texas Instruments Extends Dividend Growth Streak to 23 Years with 7% Raise
This article is originally published at Insider Monkey.


